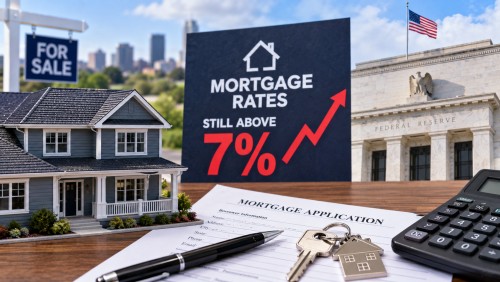
Homebuyers in the United States are facing increased borrowing costs as mortgage rates persist above 7%, a consequence of the Federal Reserve’s recent decision to hike its interest-rate range. This move, aimed at curbing inflation which remains above the Fed’s 2% target, has indirectly affected mortgage rates, making home financing more expensive.
As of September 17, 2026, the average rate for a 30-year fixed mortgage stood at 7.37%, a substantial increase from 5.75% in March. Similarly, the average 15-year mortgage rate reached 6.62%. These elevated rates translate to higher monthly payments for potential homeowners, potentially limiting the affordability of purchasing a house.
While mortgage rates are influenced by a variety of factors including financial markets, inflation expectations, and investor demand, they do not move in lockstep with the Federal Reserve’s policy rate. This means that the recent rate hike by the Fed doesn’t directly equate to a similar rise in mortgage rates, though it contributes to the overall upward trend.
For those looking to mitigate these costs, options such as securing rates below the national average might be available, depending on an individual’s credit score, down payment, lender, and loan terms. Additionally, paying mortgage points upfront can lower the interest rate, though it increases initial costs at closing. Adjustable-rate mortgages present another alternative, albeit with the risk of rate changes after an initial fixed period.
Refinancing has also become more costly, with the average 30-year refinance rate at 7.41% and the 15-year refinance rate at 6.75%. Homeowners with existing mortgages at lower rates might find refinancing less appealing unless potential savings justify the expenses involved.
The future trajectory of mortgage rates will hinge on several variables, including inflation trends, economic conditions, and expectations regarding further decisions by the Federal Reserve. While rates might fluctuate, there is no certainty that waiting will lead to lower borrowing costs, leaving homebuyers to navigate a challenging financial landscape.